Access Your Home Equity Without Replacing Your First Mortgage Access Your Equity. Keep Your Mortgage.
Explore Arizona HELOC options that may allow you to access the equity you've built while keeping your existing first mortgage in place. Understand the numbers, compare your options, and decide what makes sense for your goals.
See how much equity you may be able to access with an Arizona HELOC—without refinancing your current first mortgage.
Easy to start • Check eligibility with a soft credit pull
Your Home Has Built-In Financial Flexibility
A HELOC may allow you to access a portion of your available equity without refinancing your entire first mortgage.
Equity does not equal available borrowing capacity. Program and borrower qualifications apply.
How Much Home Equity Could You Access?
Enter a few numbers to estimate your current home equity and see illustrative borrowing capacity at several combined loan-to-value levels.
Your Estimated Equity Snapshot
Illustrative HELOC Room
This calculator is for educational and illustrative purposes only. Results are estimates and are not an offer, approval, commitment to lend, or representation of available loan terms. Actual HELOC eligibility, maximum combined loan-to-value, rates, payments, fees and terms depend on borrower qualifications, property characteristics and lender guidelines.
See If I Qualify — Soft Credit CheckYour Home Has Equity. Accessing It Shouldn't Be Confusing.
Many Arizona homeowners have built significant equity but aren't sure how to use it. Refinancing your entire mortgage is one option—but it isn't the only option.
A HELOC may provide access to additional funds while allowing your existing first mortgage to remain in place.
Your Home Equity Is Too Valuable for Guesswork
You've spent years building equity in your home. Deciding how to use it deserves more than a quick loan quote. Understand the strategy, costs and tradeoffs before deciding how to borrow.
Clear Explanations
Understand HELOC terminology, payments, CLTV and borrowing structure.
Compare Strategies
Evaluate a HELOC alongside alternatives such as a cash-out refinance.
Arizona Guidance
Guidance focused on Arizona homeowners and property scenarios.
Advisor-Led
Focus on the financial strategy first—not simply selling a loan product.
A Simple Way to Explore Your Home Equity
Get the numbers. Understand the options. Decide from there.
Tell Me About Your Home
Start with your estimated home value, mortgage balance, desired credit line and what you're trying to accomplish.
Compare Your Options
Review potential HELOC structures, available equity, payments, costs and relevant alternatives.
Choose What Makes Sense
If a HELOC fits your goals, receive guidance through the application and closing process.
What Could Your Home Equity Help You Accomplish?
Consolidate Debt
Explore whether home equity could help restructure higher-interest obligations into a different borrowing strategy.
Home Improvements
Finance renovations, remodeling, repairs, landscaping, pools or other home projects.
Financial Flexibility
Establish access to approved credit for future planned or unexpected expenses.
Major Expenses
Explore financing for significant expenses or other major financial needs.
Real Estate Opportunities
Evaluate whether existing home equity can support another real estate strategy.
Something Else?
Start with the objective, then evaluate the financing options available to you.
HELOC or Cash-Out Refinance?
Both strategies can access home equity, but they work very differently. The right option depends on your existing mortgage, goals, costs and how you plan to use the funds.
| Feature | HELOC | Cash-Out Refinance |
|---|---|---|
| Existing first mortgage | Generally remains in place | Replaced with a new mortgage |
| How funds are accessed | Credit line; draws subject to terms | Typically a lump sum at closing |
| Rate structure | Often variable | Depends on the new first mortgage |
| Interest applies to | Generally outstanding HELOC balance | Entire new mortgage balance |
| Flexibility | Potential repeated access during the draw period, subject to terms | Cash generally distributed at closing |
| Which is better? | Depends on your existing loan, objectives, borrowing needs, costs and financial circumstances. | |
What Determines an Arizona HELOC Rate?
HELOC pricing varies by lender, borrower profile, property and market conditions. An advertised rate doesn't tell the entire story.
Credit Profile
Credit history and score can influence eligibility and pricing.
Prime Rate
Many HELOCs use an index such as prime as part of the variable-rate calculation.
Lender Margin
A lender margin may be added to the applicable index.
Combined LTV
Existing mortgage debt plus the proposed HELOC relative to property value can affect available options.
Property & Occupancy
Property type, occupancy and other characteristics may affect qualification.
Line Amount
Requested credit-line size and program thresholds can influence available terms.
What Clients Say About Working With Jeremy
Real client feedback about the guidance, communication and experience they received throughout the mortgage process.
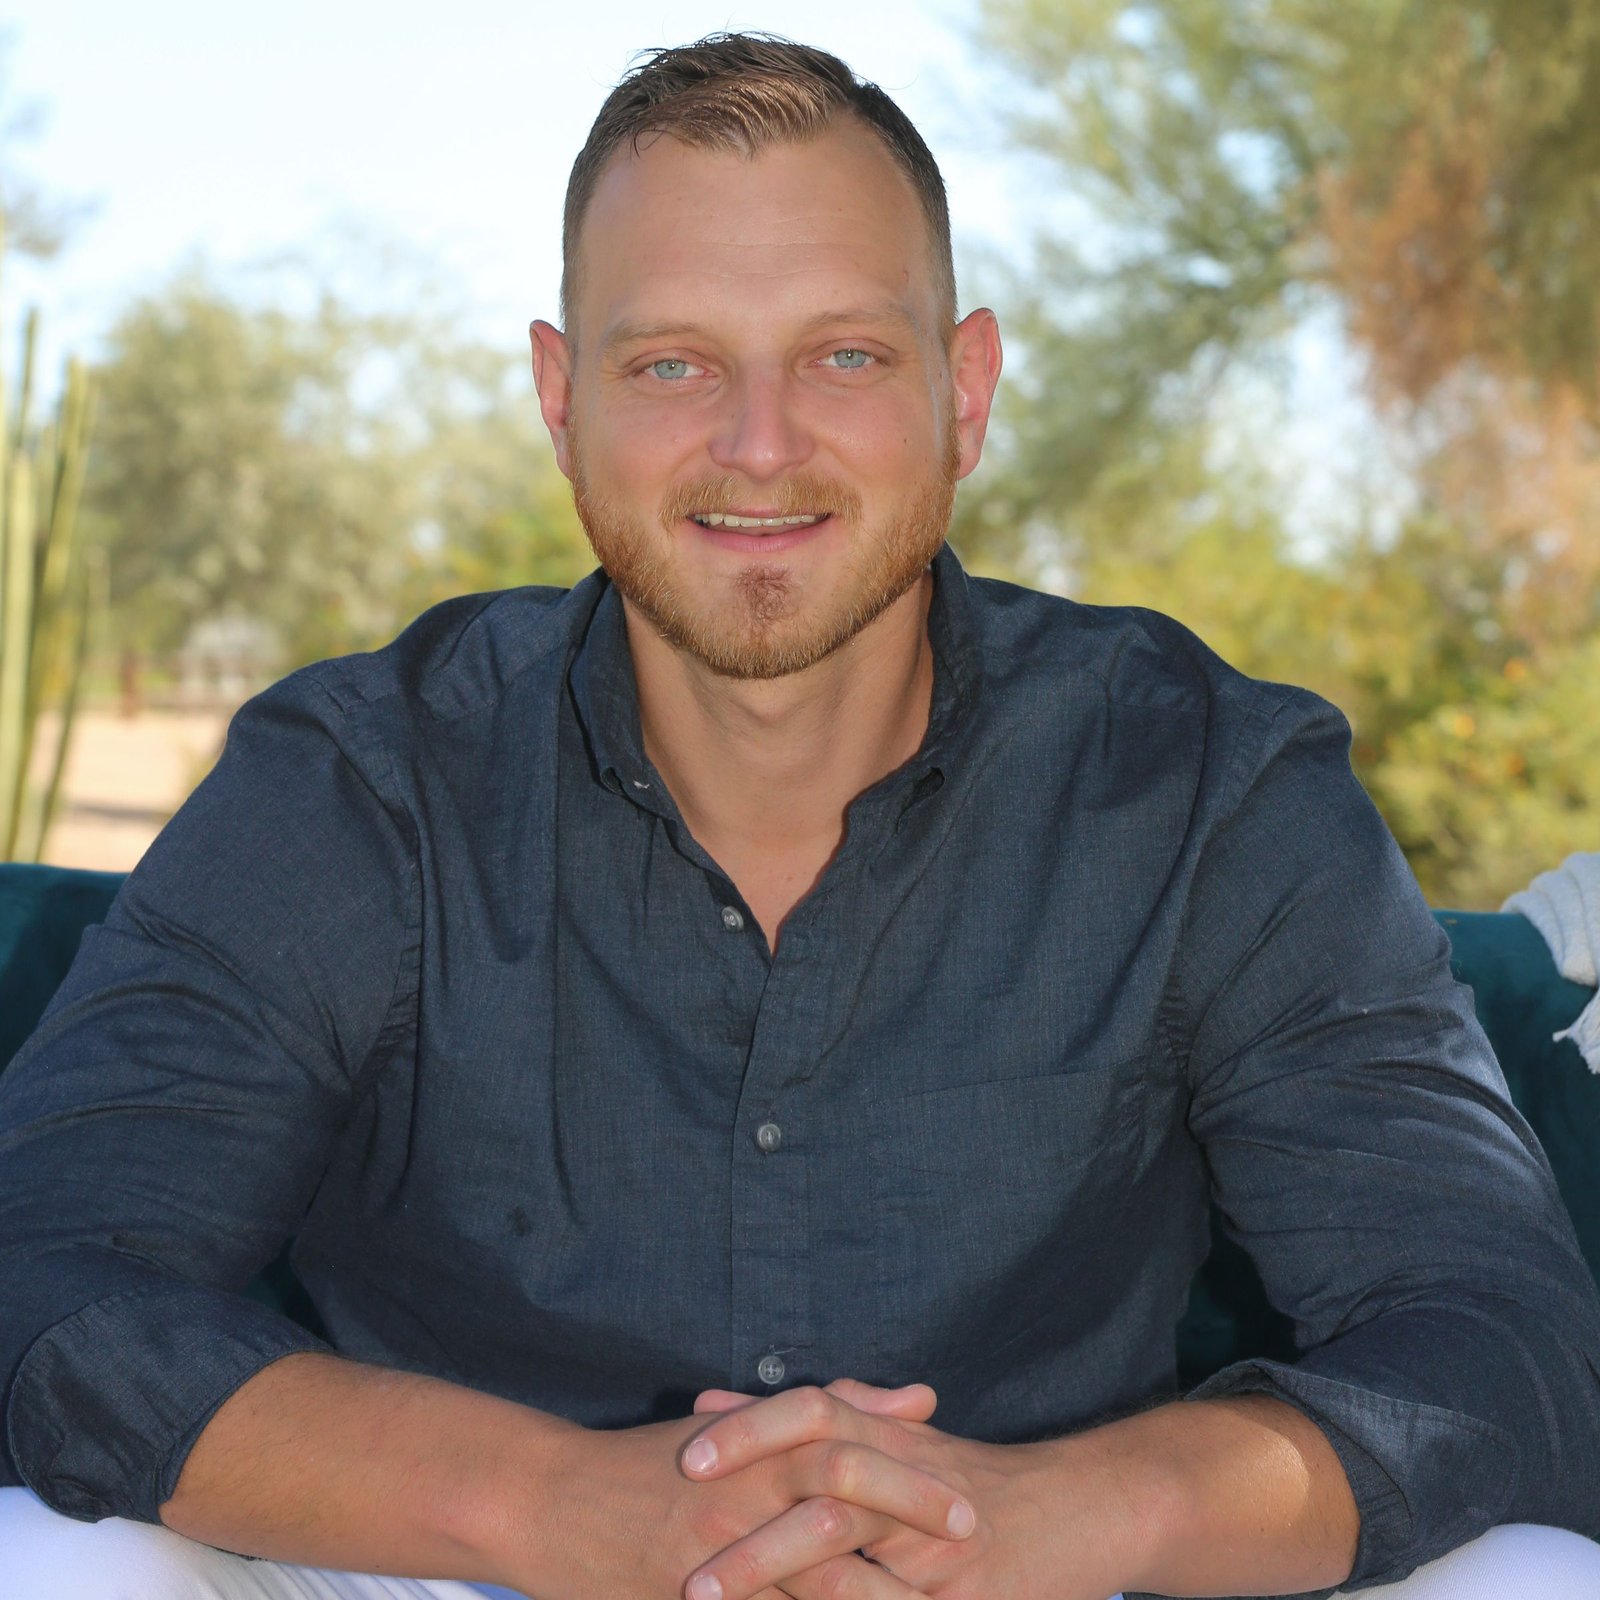
Professional Guidance When the Numbers Matter
Jeremy Boillot
Certified Mortgage Advisor | Barrett Financial Group
Jeremy Boillot is a Certified Mortgage Advisor and independent mortgage broker helping Arizona homeowners make informed mortgage and home-equity decisions.
Rather than simply quoting a loan, Jeremy helps clients understand their numbers, compare lending strategies, evaluate tradeoffs and choose financing that fits their broader financial goals.
Jeremy has been helping homebuyers and homeowners since 2014 and works through Barrett Financial Group to provide access to a variety of mortgage and home-equity solutions.
HELOC Guidance Across Arizona
Helping homeowners evaluate home-equity options throughout the Phoenix metropolitan area and communities across Arizona.
Arizona HELOC Questions
Straightforward answers to common questions about home equity lines of credit.
You've Built the Equity. Now Understand Your Options.
Find out how much equity you may be able to access, compare potential HELOC strategies, and decide what makes sense for your financial goals.
Easy to start • Check eligibility with a soft credit pull
No pressure. Just clarity.